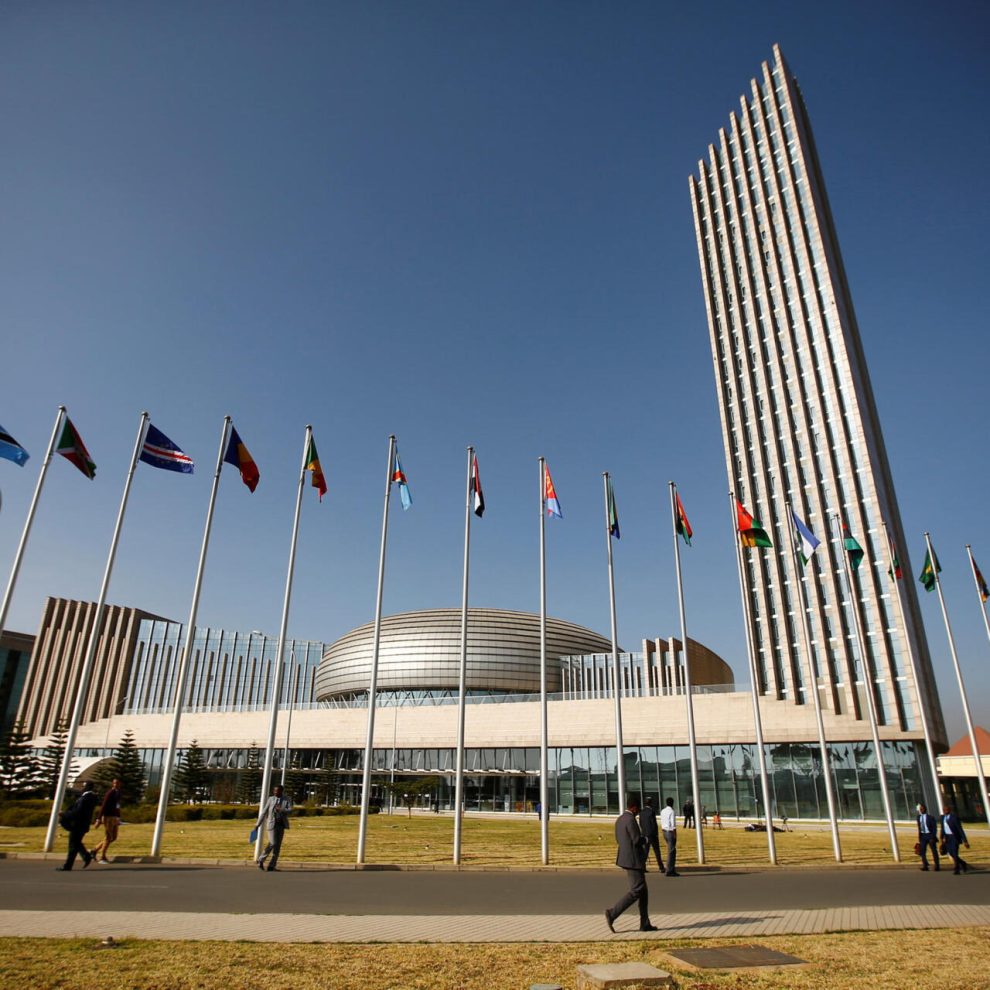

The African Union (AU) has officially launched the African Credit Rating Agency (AfCRA) in a bid to provide what leaders describe as an independent assessment of the continent’s economic potential.
The agency was unveiled on Wednesday in Port Louis, Mauritius, where its headquarters are based, in a launch broadcast live online by the African Peer Review Mechanism (APRM), the AU organ coordinating the initiative.
First approved by the AU in 2017, AfCRA aims to offer an alternative perspective to the dominant global rating agencies—Fitch Ratings, Moody’s Ratings, and S&P Global Ratings.
Speaking on behalf of Ugandan President Yoweri Museveni, Uganda’s Minister of State for Finance, Amos Lugoloobi, said the continent continues to face artificially high borrowing costs driven by international rating agencies.
“Africa does not lack economic potential, but it continues to experience high borrowing costs,” Mr Lugoloobi said, adding that while the continent should not avoid scrutiny, it requires accurate assessments rooted in its local development contexts.
‘Telling Africa’s economic story’
Chairperson of the African Union Commission, Mahmoud Ali Youssouf, emphasized that AfCRA was established to objectively evaluate sovereign risks while maintaining full operational independence to protect its credibility.
The CEO of the APRM Secretariat, Ambassador Marie-Antoinette Rose Quatre, noted that the initiative emerged from a long-standing perception gap regarding the true scale of Africa’s economy.
“Africa could no longer postpone the institutions required to tell its own economic story with rigour and credibility,” Ambassador Rose Quatre said. She stressed that AfCRA is not intended solely to compete with international agencies, but to deliver assessments that are “materially unbiased, credible, and firmly rooted in Africa’s true measure.”
Rising frustration over borrowing costs
The agency’s launch follows years of mounting frustration among African governments over sovereign credit downgrades. Countries such as Ghana and Zambia have previously argued that repeated downgrades worsened their debt vulnerabilities and pushed up international borrowing costs.
The APRM recently criticized Fitch Ratings over its assessment of Afreximbank, alleging a fundamental misunderstanding of multilateral trade finance institutions in Africa. Fitch defended its stance, stating its credit assessments follow globally uniform and transparent criteria.
According to the APRM, Africa’s capital market is valued at approximately $4tn, yet less than 5% of financial instruments by value carry a credit rating. AfCRA’s mandate will cover sovereign, sub-sovereign, and corporate issuers, focusing heavily on local-currency debt instruments.
To preserve its independence, AfCRA will not be owned by African governments despite its institutional roots in the AU.
Denys Denya, Senior Executive Vice President at Afreximbank—representing bank President Dr George Elombi—said the agency would help dismantle national rating ceilings that restrict regional corporations.
“Why should Dangote Group, which is rapidly expanding its footprint across Africa, be confined by Nigeria’s credit ratings?” Mr Denya asked, calling for an African-owned benchmark that reflects cross-border expansion.
The initiative has drawn strong support from regional leaders, including Nigerian President Bola Tinubu, who has repeatedly criticized the “Africa premium”—the cost discrepancy between perceived and actual market risk—demanding fairer evaluation metrics for developing economies.


Add Comment